OMCs Signal Support for LPG Distributor Commission Uplift
India’s major oil marketing companies (OMCs)—Indian Oil Corporation (IOCL), Bharat Petroleum Corporation Limited (BPCL), and Hindustan Petroleum Corporation Limited (HPCL)—have collectively endorsed a proposal to increase commissions paid to interim LPG distributors, according to industry representatives. The All India HP Gas Distributors Association (AIHPGDA) has formally submitted this recommendation to the petroleum ministry, marking a critical juncture in negotiations between the retail distribution network and upstream suppliers.
The alignment between OMCs and distributor bodies underscores mounting pressure within India’s liquefied petroleum gas (LPG) ecosystem, where retail margin compression has become endemic over the past 18-24 months. This development carries implications not only for distributor viability but also for last-mile accessibility in a fuel category serving over 27 crore Indian households as of 2026.
Context: Why Distributor Margins Are Under Stress
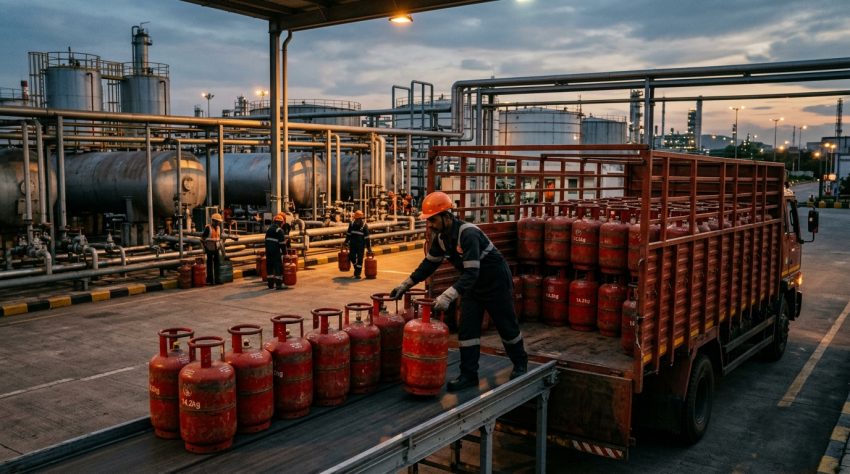
India’s LPG retail network operates on a fixed-commission model established by OMCs, with margins typically ranging between ₹1.50–₹2.50 per cylinder depending on regional factors and fuel-price volatility. Unlike petrol and diesel, which benefit from price-pass-through mechanisms, LPG retail pricing remains tightly administered by the petroleum ministry through a fortnightly review mechanism.
Interim distributors—entities that hold supply rights for specific geographic zones without owning retail outlets directly—face particular challenges. They manage inventory costs, logistics networks, and regulatory compliance while absorbing operational inflation that markedly outpaces their fixed-commission remuneration. Rising electricity costs for cylinder refilling, transportation fuel expenses, and compliance infrastructure have collectively eroded real distributor margins by an estimated 15–20% over 24 months, according to industry analysts.
The AIHPGDA’s intervention reflects growing frustration within this segment, where distributor consolidation and retail-point closures have already occurred in several states. Any widening of this gap risks fragmenting supply chains in Tier-2 and Tier-3 towns, directly undermining the government’s energy access and affordability mandates.
OMC Support: A Rare Alignment in India’s Fuel Sector
The backing from IOCL, BPCL, and HPCL represents noteworthy consensus among competitors. OMCs typically operate under ministry price caps and are incentivized to minimize operational costs; their endorsement of higher distributor commissions signals recognition that the current structure is unsustainable and risks supply-chain fragmentation.
This alignment may reflect downstream realities: if interim distributors exit the market or reduce service quality, OMCs themselves must absorb last-mile logistics complexity and costs. Supporting a modest commission increase is therefore economically rational for upstream suppliers, even as it modestly compresses their own margins in the short term.
The petroleum ministry has historically been cautious about adjusting distributor compensation, given inflationary fears and the sector’s sensitivity to political narrative around fuel affordability. However, OMC consensus provides political cover for ministry officials to approve the hike without appearing to capitulate solely to distributor advocacy.
The Ministry Decision: Timing and Scale
The petroleum ministry’s petroleum planning and analysis cell (PPAC) will ultimately determine whether the commission increase is approved, the magnitude of uplift, and implementation timeline. Industry sources indicate the proposed interim hike could range from ₹0.25–₹0.75 per cylinder, though final figures remain under negotiation.
A full ministry decision was anticipated within Q4 2026, though bureaucratic timelines in India’s energy sector are notoriously variable. The term “interim” suggests a temporary measure—potentially 12–18 months—pending a comprehensive review of the LPG distribution economics framework, which hasn’t undergone structural revision since 2019.
The timing is significant: with crude oil prices hovering near $75–$80 per barrel globally and India’s fiscal position moderately constrained, the ministry faces competing pressures. Approving distributor relief reduces pressure on politically sensitive retail pricing structures but incrementally raises the subsidy/support burden if LPG pricing for domestic consumers remains government-administered.
Implications for India’s Energy Access and Supply Stability
LPG consumption in India reached approximately 27.5 million tonnes in FY2025–26, with domestic production covering roughly 35–40% of demand, necessitating significant imports. The retail distribution network—comprising over 1.8 lakh authorized distributors and retail points—is the physical manifestation of India’s Universal LPG Scheme, which aims to ensure fuel access for cooking across income strata.
If interim distributor margins continue to compress, three risks emerge: (1) selective service withdrawal from low-density rural zones, (2) reduced investment in regulatory compliance and customer service infrastructure, and (3) potential shift toward informal or black-market transactions in underserved areas. Each compounds the government’s energy-access challenges.
Conversely, a well-calibrated commission increase—funded through OMC margin adjustment or modest pricing tweaks—strengthens supply-chain resilience and supports continuity of last-mile distribution, particularly critical as India targets household energy transition and electrification targets into the 2030s.
What Happens Next: Ministry Approval Path
The AIHPGDA’s submission to the ministry creates formal documentation for a policy decision. Following standard procedure, the petroleum ministry’s downstream regulation division will circulate the proposal internally, likely requesting OMC and state petroleum agency input. A PPAC meeting will then adjudicate and recommend either approval, rejection, or conditional acceptance to the ministry’s senior leadership.
Public announcement—if approval is granted—will likely come via a ministry press release and formal communication to OMCs, followed by updated commission schedules circulated to distributors. Any decision carries implications for state fuel taxation structures as well, since several states impose additional levies on LPG.
Conclusion: A Necessary Recalibration for India’s LPG Ecosystem
The convergence of OMC support and AIHPGDA advocacy for interim distributor commission increases signals recognition across the value chain that India’s current LPG distribution economics are misaligned with operational reality. With the ministry approval process underway, a decision is likely within the coming weeks to months.
Approval of a modest, interim commission uplift would represent rational policy recalibration rather than subsidy expansion—preserving supply-chain integrity while managing fiscal impact. For FuelWings’ audience, this development underscores the ministry’s ongoing challenge: balancing affordability optics with supply-chain sustainability. The outcome will shape distributor behavior, retail-point density, and ultimately household LPG access across India through 2027 and beyond.
By FuelWings Energy Desk · Reviewed by FuelWings Editorial Team · Published 26 October 2026 IST. FuelWings covers India & global oil, gas and fuel-price news; figures are verified against the original report and public data.
Topics: OMC commission increase, LPG retail margins, AIHPGDA, Indian fuel distribution, petroleum ministry, LPG supply chain.
Source: ET EnergyWorld (Oil & Gas) ↗